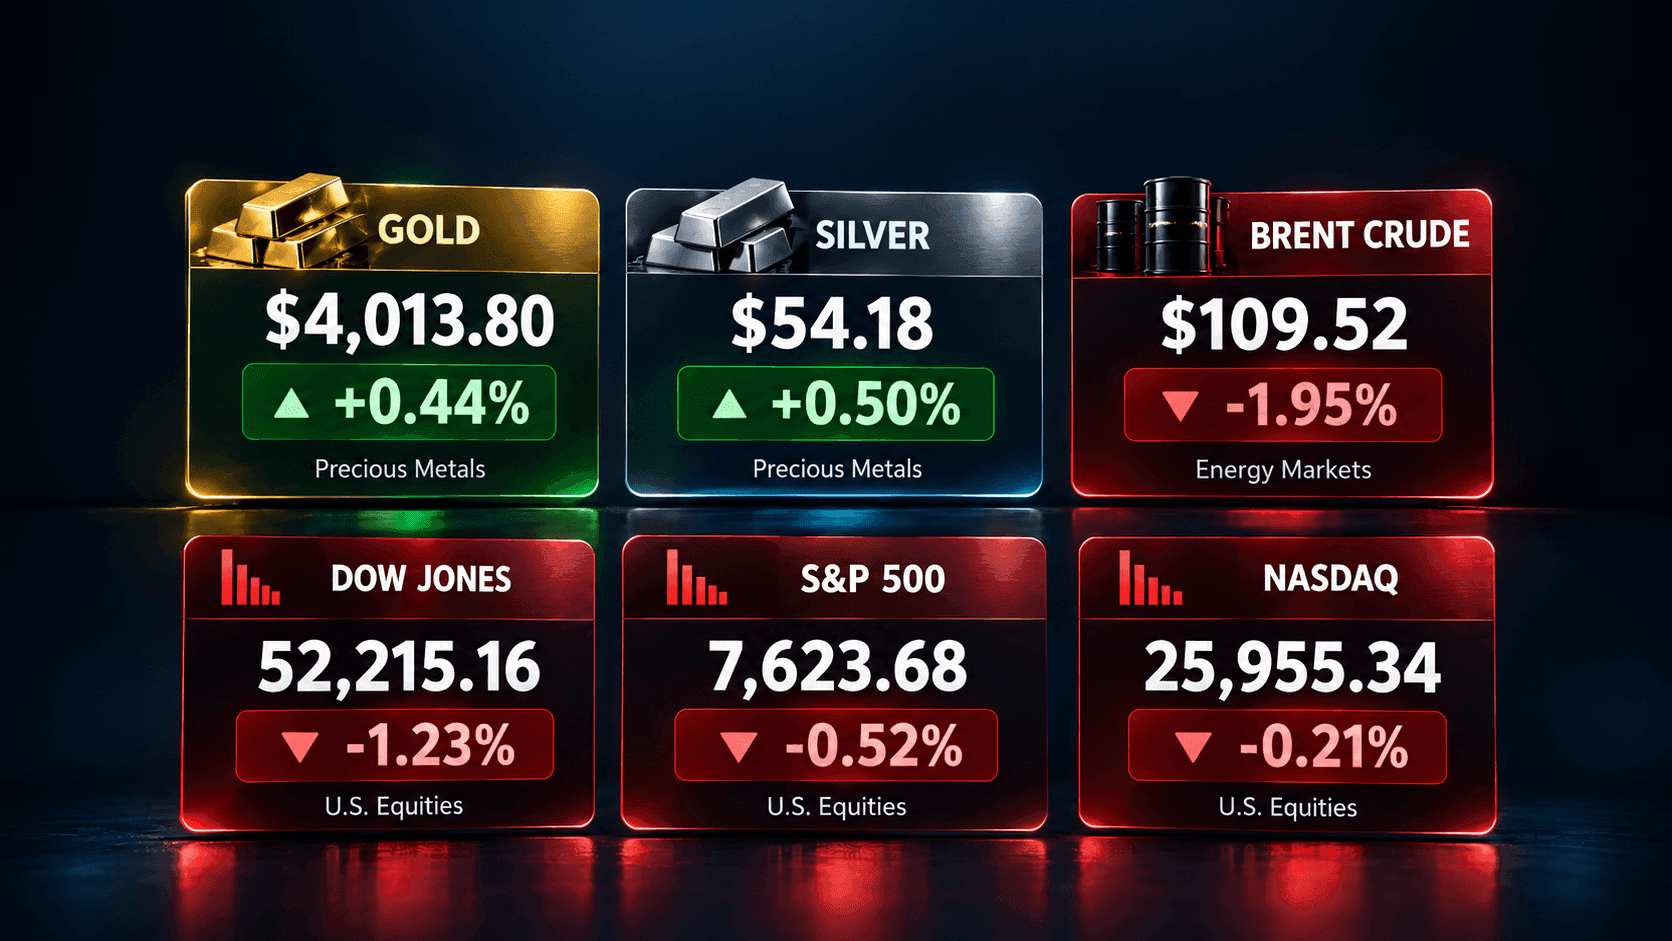
Global markets remained cautious as easing oil prices and inflation concerns supported precious metals, while Middle East diplomacy pressured crude. AI-sector weakness weighed on U.S. equities, while central bank uncertainty, shifting Treasury yields and geopolitical tensions sustained market volatility.
Today's Snapshot
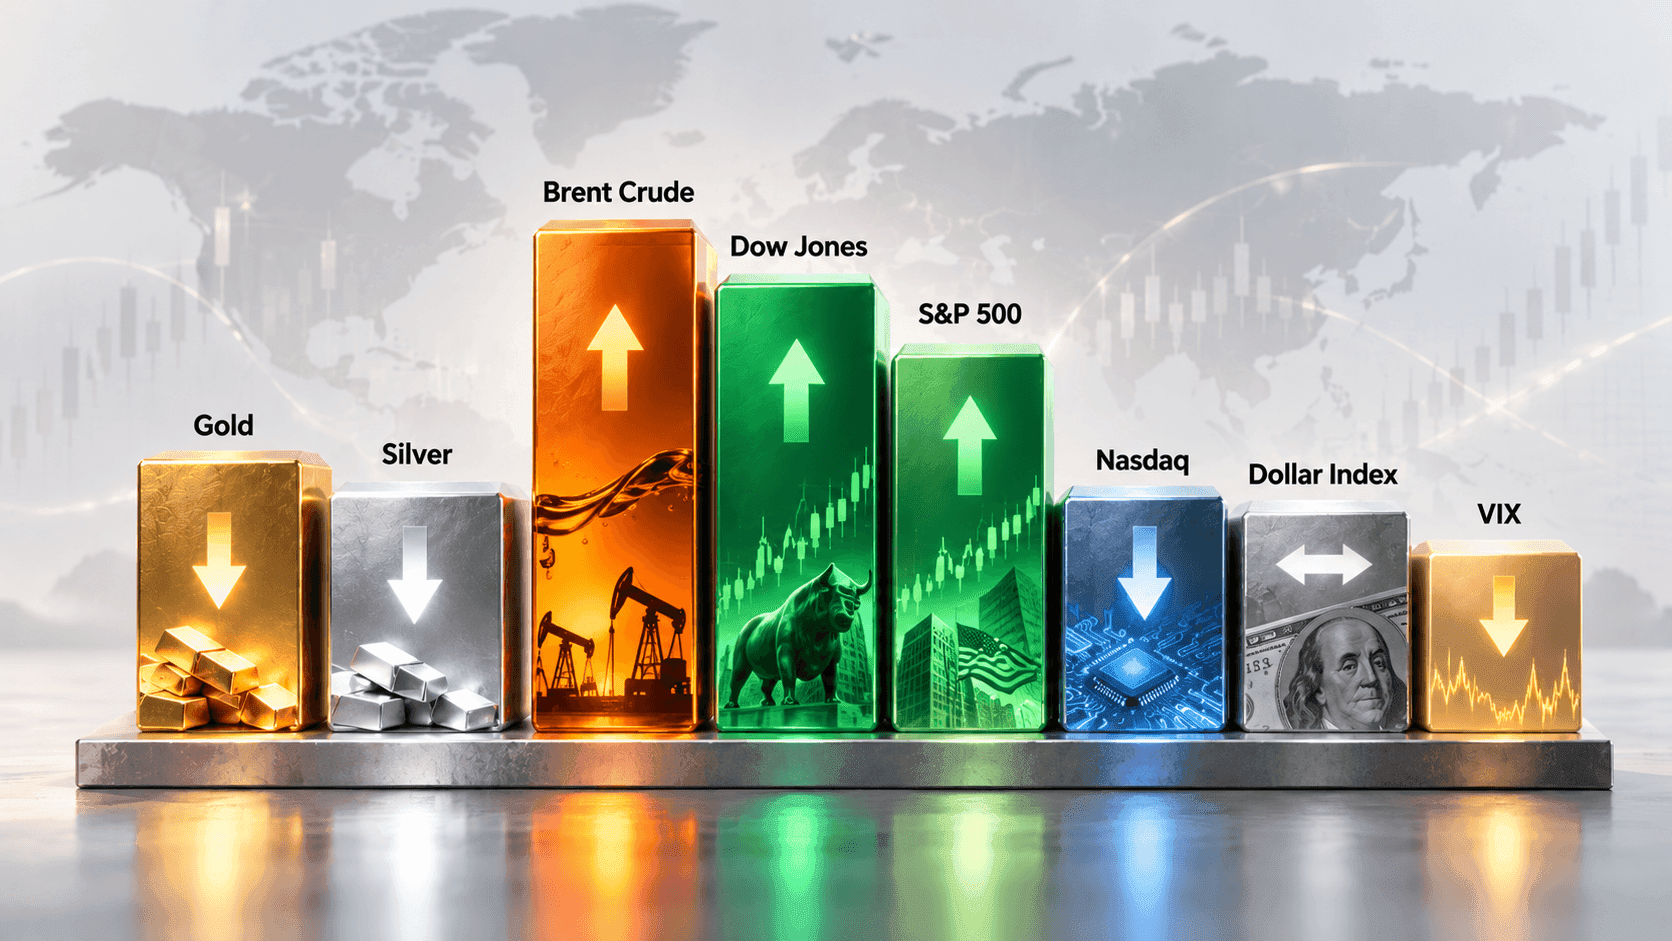
- Gold: $4,013.80/oz (+0.44%)
- Silver: $54.18/oz (+0.50%)
- Brent Crude: $109.52/bbl (-1.95%)
- Dow Jones: 52,215.16 (-652.82 pts, -1.23%)
- S&P 500: 7,623.68 (-39.75 pts, -0.52%)
- Nasdaq Composite: 25,955.34 (-53.52 pts, -0.21%)
Note: Data and market levels are based on available updates around 06:30 UTC, October 26, 2026, subject to live market fluctuations.
Global Markets
(A) Precious Metals
Gold: $4,013.80/oz (+0.44%)
Gold rose 0.44% to $4,013.80/oz as falling oil prices eased inflation concerns, supporting bullion after last week's 4% decline, its steepest weekly loss since June.
Market analyst Kyle Rodda attributed the recovery largely to relief from lower oil prices but warned that gains could remain limited ahead of the October 28 Federal Reserve decision. Markets priced approximately 75-77% odds of a December rate hike, keeping interest-rate expectations in focus.
Silver: $54.18/oz (+0.50%)
Silver gained 0.50% to $54.18/oz, recovering from last week's sharp losses as easing oil-driven inflation fears and softer interest-rate pressures improved precious-metal sentiment.
However, persistent inflation concerns and expectations of December Fed tightening limited gains. October's slowing U.S. business activity and continued price pressures added uncertainty ahead of the Federal Reserve's policy decision.
(B) Energy
Brent Crude: $109.52/bbl (-1.95%)
Brent fell 1.95% to $109.52/bbl as renewed diplomatic efforts between Iran and the United States, supported by Qatari mediation, raised hopes of reduced Middle East tensions and eased immediate supply fears.
However, continued Houthi attacks on Saudi Arabia and regional shipping risks kept supply concerns elevated. Brent had gained approximately 6.2% the previous week, highlighting the impact of geopolitical disruptions on energy prices.
(C) FX
DXY: 101.81 (+0.20%)
The U.S. Dollar Index rose 0.20% to 101.81 as euro weakness and central bank uncertainty supported the dollar. However, falling Treasury yields and AI-sector concerns limited gains ahead of the Federal Reserve meeting.
USD/JPY: 156.83 (+0.02%)
USD/JPY edged up 0.02% to 156.83, despite safe-haven demand and falling U.S. yields supporting the yen. Japanese inflation above 2.00% and 61% odds of December BOJ tightening strengthened the yen's weekly outlook.
EUR/USD: 1.1201 (-0.15%)
EUR/USD fell 0.15% to 1.1201 as Eurozone fiscal concerns, elevated borrowing costs and slowing business activity pressured the euro. Expectations of an ECB rate hold provided limited support.
GBP/USD: 1.3370 (-0.23%)
GBP/USD declined 0.23% to 1.3370 as weak UK retail sales and dollar strength pressured sterling. However, stronger UK business activity, with Composite PMI rising to 53.1, limited losses.
AUD/USD: 0.7037 (+0.26%)
AUD/USD gained 0.26% to 0.7037, supported by Australian rate-hike expectations. However, AI-sector volatility, elevated oil prices and global growth concerns limited further gains.
Volatility
The VIX climbed to 19.45, reflecting heightened market uncertainty as AI-sector weakness, falling U.S. equities and Middle East tensions increased investor caution ahead of major central bank decisions.
What Markets Are Watching
1. Federal Reserve, ECB & BOJ Decisions and Interest-Rate Expectations
Investors await the October 28 Federal Reserve decision, with rates expected to remain unchanged and markets pricing approximately 75% odds of December tightening. Upcoming ECB and Bank of Japan meetings could influence currencies and bond yields, while central bank guidance remains critical to future policy expectations.
2. Middle East Diplomacy, Oil Supply Risks & Inflation
Brent declined 1.89% to $114.51/bbl as diplomatic efforts raised hopes of de-escalation between Iran and the United States. However, renewed Houthi attacks on Saudi energy infrastructure and shipping disruptions sustained supply risks. Elevated energy prices could reinforce inflation concerns despite Monday's decline.
3. AI-Sector Earnings, Treasury Yields & Safe-Haven Demand
Investors are watching upcoming earnings from Alphabet, Microsoft and Amazon for evidence that AI investment spending can support growth. U.S. 10-year Treasury yields eased toward 4.97%, while recent equity weakness and geopolitical uncertainty continued to influence safe-haven demand and market sentiment.
“The most important quality for an investor is temperament, not intellect.”
Yesterday's Market News - October 23, 2026
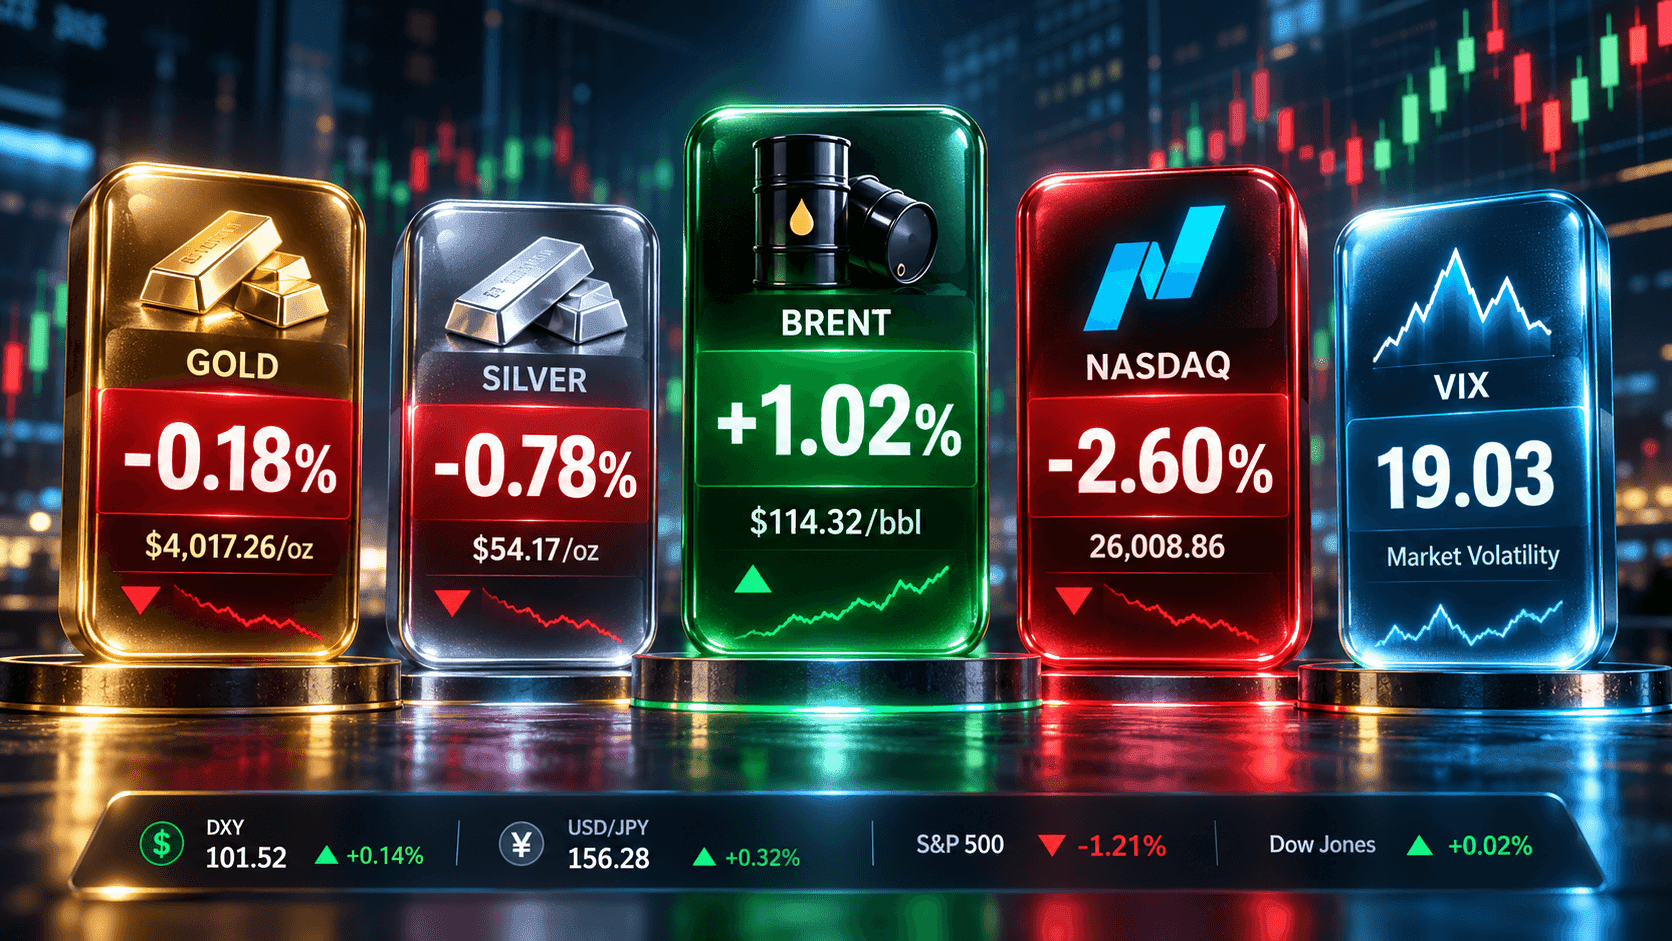
Gold Falls 0.18% to $4,017.26, Silver Drops 0.78% to $54.17 and Brent Rises 1.02% to $114.32
Read full recap →Disclaimer
This report is for informational purposes only and does not constitute investment advice, financial guidance, or a solicitation to buy or sell any financial instruments. Market data and figures are subject to change without notice. Data has been taken from sources we believe to be reliable; however, please conduct your own research before making any investment decisions. Trading leveraged or complex products carries significant risk; please ensure you understand the risks before trading.
T&Cs apply. For full terms and conditions, please visit centrinocapital.com.