Global markets remained cautious as Fed tightening expectations and rising inflation pressured precious metals, while escalating Middle East tensions lifted oil prices. Strong corporate earnings supported U.S. equities, while central bank uncertainty and geopolitical risks kept investors focused on monetary policy and market stability.
Today's Snapshot
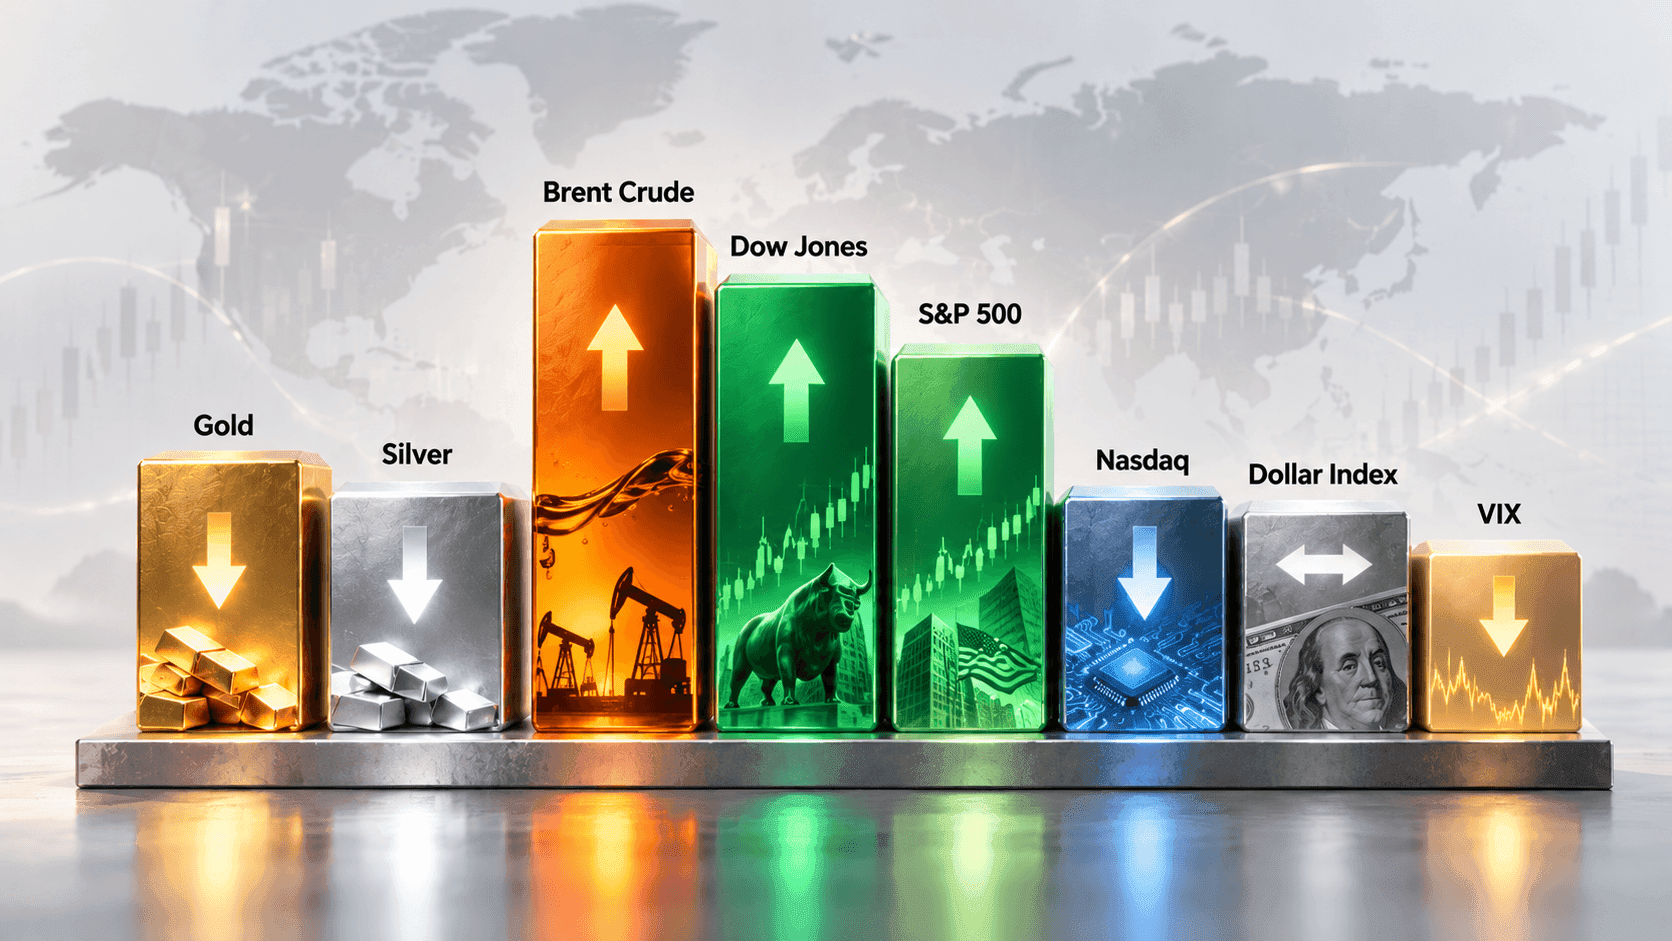
- Gold: $4,080.79/oz (-1.46%)
- Silver: $56.17/oz (-3.11%)
- Brent Crude: $111.41/bbl (+2.38%)
- Dow Jones: 52,856.09 (+360.21 pts, +0.69%)
- S&P 500: 7,757.17 (+44.60 pts, +0.58%)
- Nasdaq Composite: 26,702.86 (+278.04 pts, +1.05%)
Note: Data and market levels are based on available updates around 06:30 UTC, October 22, 2026, subject to live market fluctuations.
Global Markets
(A) Precious Metals
Gold: $4,080.79/oz (-1.46%)
Gold fell 1.46% to $4,080.79/oz as rising oil prices, inflation concerns and Fed tightening expectations pressured bullion.
Markets priced a 15% chance of an October rate hike and 91% probability of December tightening. Higher energy costs reinforced expectations of prolonged elevated interest rates ahead of the October 27-28 Fed meeting.
Silver: $56.17/oz (-3.11%)
Silver dropped 3.11% to $56.17/oz, pressured by higher interest-rate expectations, a stabilizing dollar and rising energy costs.
Brent above $111/bbl intensified inflation concerns, while 91% odds of December Fed tightening and industrial demand uncertainty weakened sentiment.
(B) Energy
Brent Crude: $111.41/bbl (+2.38%)
Brent rose 2.38% to $111.41/bbl as attacks on Saudi energy infrastructure and escalating Middle East tensions heightened supply concerns.
U.S. crude inventories fell 3.06 million barrels to 412.5 million, exceeding expectations. Washington's plan to release 315,000 barrels through emergency heating-oil loans offered limited relief.
(C) FX
DXY: Around 101.79
The U.S. Dollar Index stabilized after recent declines as Fed tightening expectations and higher-for-longer interest rates supported the greenback. Strong U.S. growth expectations offered support, while recent gains in commodity-linked currencies limited recovery.
Markets expected the Fed to hold rates at 3.75% - 4.00% in October, with a potential hike in December.
USD/JPY: Around 158.00
USD/JPY held near 158.00 as Bank of Japan tightening expectations and intervention concerns limited yen weakness.
Markets anticipated a rate hold next week, with the next increase to 1.50% expected in early 2027. Uncertainty over U.S. interest rates kept the pair range-bound.
EUR/USD: Above 1.1200
EUR/USD remained above 1.1200, pressured by French fiscal uncertainty, political unrest and European energy risks.
French 10-year bond yields reached their highest since 2022, while markets expected the ECB to hold rates at 2.50% next week. Persistent budget concerns limited euro recovery.
GBP/USD: 1.3395
GBP/USD held near 1.3395, supported by stronger UK inflation and expectations of further Bank of England tightening.
UK inflation reached 3.5%, above the 3.4% forecast, lifting sterling to a one-month high of 1.3409 earlier in the week. Dollar stabilization subsequently limited gains.
AUD/USD: 0.7025
AUD/USD held near 0.7025, supported by hawkish central bank comments and expectations of further Australian rate increases.
Deputy Governor Andrew Hauser warned that the inflation outlook had materially worsened, partly due to rising oil prices, strengthening expectations of a possible November rate hike.
High-Impact Economic Events
| Country | Release | Actual | Forecast | Previous | Time |
|---|---|---|---|---|---|
| United States | Unemployment Claims | - | 200K | 199K | 12:30 PM (GMT-04:00) |
Note: These economic events are for informational purposes only. Please conduct your own research before making any market decisions.
Volatility
The VIX declined to 16.68, reflecting easing market anxiety and strong corporate earnings, while Fed uncertainty, rising oil prices and Middle East tensions sustained risks.
What Markets Are Watching
1. Federal Reserve Policy, U.S. Employment Data & Global Central Banks
Investors are focused on the October 27-28 Federal Reserve meeting, with markets pricing a 15% chance of an October rate hike and 91% probability of December tightening. Today's U.S. unemployment claims, forecast at 200K versus 199K previously, could provide further insight into labor-market conditions. Upcoming ECB, Bank of Japan and Bank of Canada decisions are adding to monetary policy uncertainty.
2. Middle East Escalation, Oil Supply Risks & U.S. Reserve Intervention
Brent rose 1.77% to $110.75/bbl following renewed Houthi attacks on Saudi energy infrastructure and vessels near the Persian Gulf. A 3.06-million-barrel decline in U.S. crude inventories reinforced supply concerns. Washington's plan to loan 315,000 barrels of emergency heating oil offered limited relief, while regional disruptions sustained inflation risks.
3. U.S. Equity Recovery, Corporate Earnings & European Political Risks
U.S. equities strengthened as corporate earnings supported investor confidence, lifting the Dow 0.69%, S&P 500 0.58% and Nasdaq 1.05%. However, rising borrowing costs and energy inflation remained concerns for corporate profitability. Meanwhile, French fiscal uncertainty and elevated government bond yields pressured European sentiment as investors assessed whether the earnings-led recovery could withstand tighter monetary conditions.
“The stock market is a device for transferring money from the impatient to the patient.”
Yesterday's Market News - October 21, 2026
Gold Falls 0.24% to $4,115.66, Silver Drops 1.26% to $57.26 and Brent Rises 1.47% to $110.39
Read full recap →Sources
- 1. Gold, Silver & Federal Reserve Rate Expectations - Reuters
- 2. U.S. Dollar, British Pound, Australian Dollar & Central Bank Policy - Reuters
- 3. Brent Crude, Saudi Arabia Attacks & U.S. Oil Inventories - Reuters
- 4. U.S. Emergency Heating Oil Reserve & Energy Prices - Reuters
- 5. High-Impact Economic Events - Forex Factory
Disclaimer
This report is for informational purposes only and does not constitute investment advice, financial guidance, or a solicitation to buy or sell any financial instruments. Market data and figures are subject to change without notice. Data has been taken from sources we believe to be reliable; however, please conduct your own research before making any investment decisions. Trading leveraged or complex products carries significant risk; please ensure you understand the risks before trading.
T&Cs apply. For full terms and conditions, please visit centrinocapital.com.