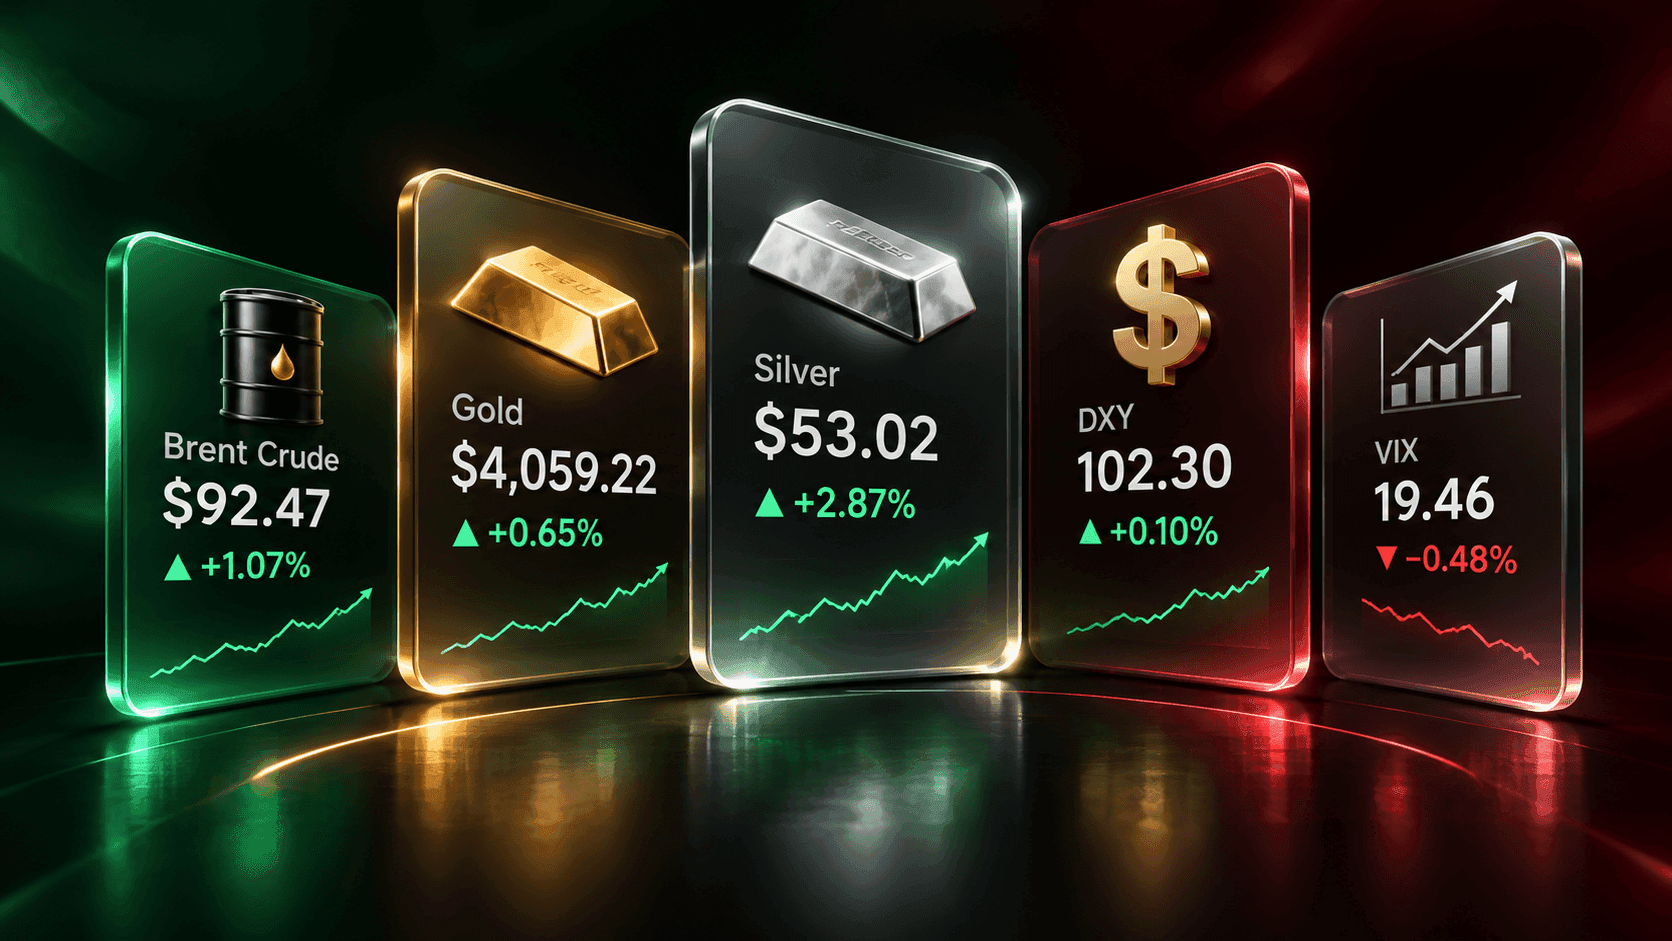
Global markets remained cautious as stronger U.S. inflation and Fed tightening expectations supported the dollar. Gold and silver rebounded from recent losses, while Brent advanced amid renewed Strait of Hormuz supply risks. Rising Treasury yields continued to pressure equities and market sentiment.
Today's Snapshot
- Gold: $4,059.22/oz (+0.65%)
- Silver: $53.02/oz (+2.87%)
- Brent Crude: $92.47/bbl (+1.07%)
- Nasdaq Composite: 25,065.88 (-187.27 pts, -0.74%)
- S&P 500: 7,520.93 (-29.01 pts, -0.38%)
- Dow Jones: 52,231.89 (-157.86 pts, -0.30%)
Note: Data and market levels are based on available updates around 05:30 UTC, November 11, 2026, subject to live market fluctuations.
Global Markets
(A) Precious Metals
Gold: $4,059.22/oz (+0.65%)
Gold rose 0.65% to $4,059.22/oz, recovering from Tuesday's nearly 3% decline as technical buying and short-covering supported prices. However, stronger U.S. inflation and 100% expectations of a December Fed rate hike, up from 84%, limited gains amid elevated Treasury yields.
Silver: $53.02/oz (+2.87%)
Silver gained 2.87% to $53.02/oz as bargain buying and gold's recovery supported precious metals. However, a stronger dollar, elevated Treasury yields and increased Fed rate-hike expectations continued to restrict gains.
(B) Energy
Brent Crude: $92.47/bbl (+1.07%)
Brent rose 1.07% to $92.47/bbl as renewed Strait of Hormuz shipping attacks and disruptions at Russia's Ust-Luga port raised supply concerns. Reports of 37 vessel attacks in October supported prices, while U.S.-Iran truce hopes and a 9-million-barrel rise in U.S. crude inventories limited gains.
(C) FX
DXY: 102.30 (+0.10%)
The dollar index rose 0.10% to 102.30 as stronger U.S. inflation and hawkish Fed comments supported the greenback. December rate-hike expectations strengthened, with an 85% probability of a 25-basis-point increase.
USD/JPY: 158.82
USD/JPY held near 158.82 as rising U.S. Treasury yields and Fed tightening expectations supported the dollar. The 10-year yield reached 4.996%, limiting yen recovery.
EUR/USD: 1.1163
EUR/USD remained near 1.1163 as dollar strength and higher U.S. Treasury yields pressured the euro. Investors awaited ECB President Lagarde's remarks for policy signals.
GBP/USD: 1.3346
GBP/USD held near 1.3346 as stronger U.S. inflation and hawkish Fed expectations restricted sterling gains, with Treasury yields approaching 5%.
AUD/USD: 0.6875 (+0.10%)
AUD/USD gained 0.10% to 0.6875 as modest buying supported recovery, although dollar strength and increased Fed rate-hike expectations limited gains.
NZD/USD: 0.5606
NZD/USD remained near 0.5606 as a firmer dollar and New Zealand's post-election uncertainty restricted gains amid elevated U.S. Treasury yields.
USD/CAD: 1.4194 (+0.53%)
USD/CAD rose 0.53% to 1.4194 as stronger U.S. inflation and Fed tightening expectations supported the dollar, while oil-price uncertainty weighed on the Canadian dollar.
High-Impact Economic Events
| Country | Release | Forecast | Previous | Time |
|---|---|---|---|---|
| Euro | ECB President Lagarde Speaks | - | - | 9:45 AM (GMT+02:00) |
Note: These events are for informational purposes only. Please conduct your own research before making any market decisions.
Volatility
The VIX eased to 19.46 from 19.92, indicating reduced market anxiety, although stronger U.S. inflation, hawkish Fed expectations and elevated Treasury yields continued to weigh on sentiment.
What Markets Are Watching
1. U.S. Inflation, Treasury Yields & Federal Reserve Rate Expectations
October's stronger-than-expected inflation strengthened expectations of further monetary tightening, pushing the U.S. 10-year Treasury yield towards 5%. Markets now price a 100% probability of a December rate increase, with approximately 85% favouring a 25-basis-point hike and 15% expecting 50 basis points. Continued hawkish Fed remarks could strengthen the dollar and pressure gold, equities and other interest-rate-sensitive assets.
2. Middle East Shipping Attacks, Oil Supply & U.S.-Iran Negotiations
Brent rebounded 1.10% to $92.53/bbl as persistent attacks on vessels in the Strait of Hormuz challenged expectations of an imminent U.S.-Iran de-escalation. Reports of 37 ship attacks in October, fresh tanker incidents and a Russian port drone strike heightened supply concerns. However, an estimated 9 million-barrel increase in U.S. crude inventories and diplomatic uncertainty could limit oil's recovery.
3. Global Equities, AI-Sector Valuations & ECB Policy Outlook
U.S. equities retreated following stronger inflation, with the Nasdaq falling 0.74%, the S&P 500 declining 0.38% and Nvidia losing 5.47%. Asian markets showed selective strength, with Taiwan advancing 2.1% and South Korea gaining 1.6% amid continued AI-chip demand. Investors are also monitoring ECB President Christine Lagarde's speech for indications of the eurozone policy outlook.
“The stock market is filled with individuals who know the price of everything, but the value of nothing.”
Yesterday's Market News - November 9, 2026
Gold Rises 1.28% to $4,122.57, Silver Gains 1.77% to $52.87 and Brent Falls 1.24% to $97.10
Read full recap →Disclaimer
This report is for informational purposes only and does not constitute investment advice, financial guidance, or a solicitation to buy or sell any financial instruments. Market data and figures are subject to change without notice. Data has been taken from sources we believe to be reliable; however, please conduct your own research before making any investment decisions. Trading leveraged or complex products carries significant risk; please ensure you understand the risks before trading.
T&Cs apply. For full terms and conditions, please visit centrinocapital.com.